


Lawyer payment plans make legal services more affordable by allowing clients to spread costs over time instead of paying everything upfront. Common options include installments, retainers, flat fees, contingency fees, limited-scope services, and financing.
Common Lawyer Payment Plan Options
Law firms use several methods to make legal fees more manageable. A traditional installment plan is only one possibility. Depending on your case, you may encounter hourly billing with a retainer, fixed fees paid in installments, contingency fees, limited-scope representation, credit-card payments, or third-party financing.
| Payment option | How it generally works | Often suitable for |
| Installment plan | Legal fees are divided into scheduled payments | Family, immigration, criminal defense, estate, and other matters |
| Retainer plus monthly billing | Client deposits money upfront and pays additional bills as work continues | Litigation and matters with uncertain workloads |
| Flat-fee installments | A fixed legal fee is divided into several payments | Predictable legal services |
| Contingency fee | Attorney receives an agreed percentage if money is recovered | Certain injury and financial recovery cases |
| Limited-scope representation | Client pays an attorney for selected parts of a matter | People who can handle some tasks themselves |
| Credit card | Legal bill is charged to a card and repaid to the card issuer | Short-term financing when repayment is manageable |
| Third-party financing | A separate lender finances legal expenses | Clients who qualify and understand borrowing costs |
| Legal aid or pro bono help | Eligible clients receive free or reduced-cost legal assistance | Qualifying people with limited financial resources |
The lowest monthly payment is not automatically the cheapest arrangement. Compare the total amount you are likely to pay and what services you receive.
Monthly Installment Plans
A monthly payment arrangement is one of the simplest ways to make an attorney’s fee manageable. Instead of requiring the entire amount before beginning work, the firm may accept an initial deposit followed by weekly, biweekly, or monthly payments.
Suppose an attorney charges a $6,000 fixed fee. Instead of requiring $6,000 immediately, the agreement might require $1,500 upfront followed by nine payments of $500. This structure lowers the initial financial barrier without changing the total fee, assuming no financing charges or additional expenses apply.
Payment arrangements vary considerably among law firms. A lawyer may require automatic payments, a minimum initial deposit, or complete payment before a particular stage of the case. Ask what happens if your circumstances change or you miss a payment.
The agreement should also explain whether filing fees, expert witnesses, investigators, travel, transcripts, medical records, or other case expenses are included. A “$500 monthly payment” tells you very little unless you know what the payment covers.
Retainers With Ongoing Payments
Some lawyers charge by the hour and require an advance deposit commonly called a retainer. The attorney bills time against the deposited funds according to the fee agreement.
For example, a client might deposit $3,000 before work begins. As the attorney performs services, fees are charged according to the agreed billing rate. The client may then receive periodic invoices or be required to replenish the account when its balance drops below a specified amount.
This arrangement is common when the amount of work cannot be predicted accurately. A case that settles quickly may require substantially less attorney time than one involving extensive discovery, hearings, negotiations, or trial.
Under the American Bar Association’s Model Rule 1.5, lawyer fees and expenses must be reasonable, and the basis or rate of the fee should be communicated to the client, preferably in writing. State rules can impose additional requirements.
Before paying a retainer, ask how frequently you will receive invoices, what billing increments the firm uses, which employees bill for their work, and whether you must maintain a minimum account balance.
Flat Fees Paid in Installments
A flat fee establishes a predetermined price for defined legal work. Some attorneys allow that amount to be paid according to a schedule.
Flat fees can make budgeting easier because the client knows the agreed attorney fee before representation begins. They are commonly used when the lawyer can reasonably predict the work involved.
However, “flat fee” does not automatically mean “everything included.” A $2,500 fee might cover document preparation and a particular hearing but exclude an appeal, expert testimony, additional motions, or unexpected litigation.
Read the scope section of the agreement carefully. Ask what event marks the completion of the lawyer’s services and what additional work would require another fee.
Contingency Fee Arrangements
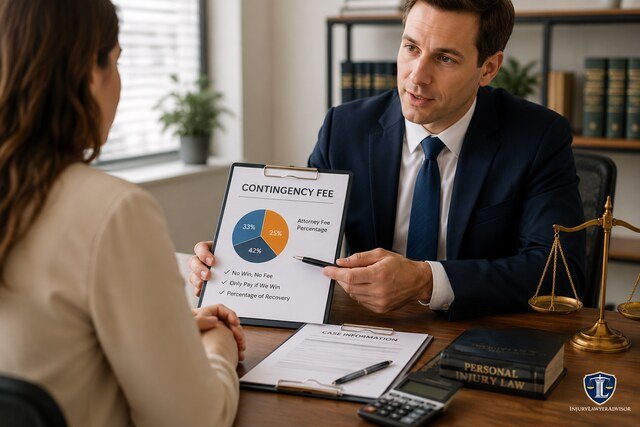

A contingency arrangement can eliminate or significantly reduce upfront attorney fees in certain cases. Instead of receiving regular legal-fee payments, the attorney receives an agreed portion of a financial recovery if the case succeeds.
Contingency fees are commonly associated with cases seeking monetary compensation, but they are not permitted for every type of legal matter.
ABA Model Rule 1.5 states that contingency agreements must be in writing and signed by the client. The agreement should explain how the fee is calculated, how litigation expenses are handled, and whether expenses are deducted before or after the lawyer’s percentage is calculated. The ABA Model Rules also prohibit contingency fees for representing criminal defendants and certain domestic-relations arrangements. State law may establish additional restrictions or requirements.
Consider a hypothetical $100,000 settlement. If a contract provides for a 33% attorney fee, the fee calculation would begin around $33,000, but that does not necessarily tell you the client’s final amount. Case expenses, liens, medical bills, taxes where applicable, and the contract’s method of calculating costs can affect the final distribution.
Ask for a clear explanation using actual numbers before signing.
Limited-Scope Legal Representation
Limited-scope representation can reduce costs by paying a lawyer only for specific parts of a matter rather than full representation from beginning to end.
For example, you might prepare routine documents yourself while hiring an attorney to review them, advise you before a hearing, negotiate a particular issue, or handle one complex portion of the case.
ABA Model Rule 1.2 permits lawyers to limit the scope of representation when the limitation is reasonable under the circumstances and the client gives informed consent. Local court procedures and state professional-conduct rules can affect how limited representation works.
This option works best when responsibilities are extremely clear. The written agreement should identify what the lawyer will handle and what remains your responsibility. Missing a filing deadline because each side assumed the other person was responsible can be far more expensive than the savings produced by limited representation.
Paying a Lawyer With a Credit Card
Many law firms accept credit cards, which effectively lets the credit-card issuer provide the payment plan. The attorney receives payment while you repay the card according to your account terms.
Convenience comes with a potential drawback: interest.
The Consumer Financial Protection Bureau explains that many credit-card companies calculate interest daily using account balances. Carrying the balance instead of paying it in full can therefore increase the total cost significantly.
Suppose you place a $5,000 legal bill on a credit card. Your legal services still cost $5,000, but the amount ultimately paid to finance that purchase can be higher if interest accrues for months or years.
Promotional financing deserves particular attention. Some offers use deferred interest rather than a simple permanent 0% rate. The CFPB warns that failing to pay the entire qualifying balance within the promotional period can, depending on the arrangement, trigger interest dating back to the original purchase.
Read the financing terms rather than focusing only on the minimum monthly payment.
Third-Party Legal Financing
Some firms work with financing companies that allow eligible clients to borrow money for legal expenses. The lender pays or finances the legal bill, while the client makes scheduled repayments.
Approval may depend on creditworthiness, income, loan amount, or the lender’s underwriting standards. Interest rates, origination charges, late fees, repayment periods, and other terms can vary.
Compare financing based on total repayment, not merely the advertised monthly amount.
For example, a payment of $250 per month may appear more affordable than $400 per month, but the lower payment could become more expensive if it continues for substantially longer and includes interest.
Before borrowing, request the APR, total repayment estimate, loan term, fees, prepayment rules, and consequences of late payments.
Ask the Lawyer to Adjust the Initial Retainer
If the quoted deposit is unaffordable, you can ask whether the attorney will accept a smaller initial payment followed by more frequent installments.
You might say that you can reliably pay $600 today and $400 every two weeks rather than a $2,000 deposit. A lawyer does not have to accept that proposal, but a realistic payment schedule can be more useful than simply asking for a discount.
You can also ask whether payments can correspond with stages of the case. A fixed-fee matter, for example, might be divided between hiring, filing, negotiation, and a scheduled hearing.
Do not agree to payments you already know you cannot maintain. A sustainable arrangement is usually more useful than an aggressive payment schedule that creates problems halfway through representation.
How to Compare Lawyer Payment Plans
Start by asking for the anticipated total cost. Exact predictions are not always possible, especially in litigation, but an attorney may be able to provide a range or explain which events are likely to increase fees.
Then ask these questions:
- How much must I pay before work begins?
- What will I pay each month?
- Is interest charged?
- Are there financing or administrative fees?
- What services are included?
- Which expenses are billed separately?
- What happens if the case lasts longer than expected?
- What happens if I miss a payment?
- Can the payment schedule be modified?
- What happens to unused advance funds?
- Will I receive itemized bills?
- What legal work stops when the agreed representation ends?
The goal is to compare both cash flow and total cost.
Imagine Attorney A requires $4,500 upfront. Attorney B accepts $1,000 initially and seven monthly payments of $500, totaling the same $4,500. Attorney C offers financing requiring smaller payments but produces a total repayment of $5,300 after financing costs.
Attorney C may have the easiest monthly payment, while Attorney A or B may ultimately cost less. Your decision should account for affordability, total expense, scope of work, and the lawyer’s suitability for your case.
Ways to Reduce Legal Costs Without Giving Up Necessary Help
Payment plans address when you pay. Sometimes the better solution is reducing the amount of attorney time you need to purchase.
Ask whether you can organize documents, prepare a timeline, gather requested records, and communicate questions efficiently instead of sending numerous separate messages. For hourly representation, unnecessary attorney time may increase fees.
Limited-scope services may also reduce costs when appropriate. An attorney could advise you on strategy or review documents while you complete permissible administrative tasks yourself.
You can also compare several lawyers. The cheapest attorney is not automatically the best choice, but fee structures can differ considerably even when lawyers provide similar services.
For certain civil legal problems, eligible low-income individuals may qualify for free legal assistance. The Legal Services Corporation funds nonprofit civil legal-aid organizations throughout the United States and provides a tool for finding local programs.
Red Flags to Check Before Signing a Payment Agreement
Do not evaluate a lawyer solely by whether the monthly payment fits your budget.
Be cautious when you cannot obtain a clear explanation of the fee structure, expenses, scope of representation, or circumstances that could create additional charges. The ABA’s guidance emphasizes communicating the basis or rate of attorney fees and expenses, and written terms can reduce misunderstandings.
Also examine agreements that focus heavily on a low initial payment without explaining what happens later. A $300 starting payment may sound attractive, but it provides little useful information if another $4,000 becomes due before an important hearing.
Never assume that “payment plan available” means interest-free, that a retainer represents the entire cost, or that a flat fee covers every possible development.
What If You Cannot Afford Any Lawyer Payment Plan?
If even a reduced payment arrangement is beyond your budget, investigate legal aid, nonprofit organizations, law-school clinics, court self-help programs, bar-association referral services, and attorneys who provide pro bono or limited-scope assistance.
Legal Services Corporation-funded organizations provide civil legal help to eligible low-income Americans in areas that can include housing, family safety, public benefits, employment-related matters, and other critical civil issues. Eligibility and available services depend on the organization and case.
Criminal cases operate differently. People facing qualifying criminal proceedings may have constitutional or statutory rights to appointed counsel, depending on the circumstances. Do not assume civil legal-aid rules apply to a criminal defense case.
If a court deadline is approaching, investigate assistance promptly. Financial difficulties do not automatically extend filing deadlines or court dates.
FAQ’s
Do lawyers usually let clients make monthly payments?
Some do, while others require an advance retainer, flat fee, contingency arrangement, or another billing structure. Availability depends on the law firm, type of case, expected workload, and attorney’s policies. Ask about financing during the initial consultation rather than assuming the entire fee must be paid immediately.
How much should I put down on a lawyer payment plan?
There is no universal minimum deposit. The amount depends on the lawyer, fee structure, complexity of the matter, anticipated early work, and local practices. Instead of focusing only on the deposit, ask for the expected total cost and payment obligations throughout the case.
Can I negotiate attorney payment terms?
You can ask. A lawyer may be willing to modify the deposit, payment dates, frequency, scope of representation, or fee structure. The attorney does not have to accept the proposal, and professional-conduct rules and the nature of the case can limit available arrangements.
What happens if I miss a lawyer payment?
The consequences depend on your agreement and applicable law. A firm may charge amounts permitted by the agreement, request immediate payment, modify future services, or seek to withdraw from representation when legally and ethically permitted. Court approval may be required for withdrawal in an active case. Review the agreement before signing and contact the firm early if you anticipate a payment problem.
Is a payment plan better than using a credit card?
A direct interest-free installment arrangement may cost less than carrying a credit-card balance, but every arrangement is different. Compare the total amount due, interest, fees, payment period, and consequences of late payments. Credit-card interest can substantially increase borrowing costs when balances remain unpaid.
Conclusion
The best lawyer payment plan option is not necessarily the one with the smallest initial payment. A good arrangement makes legal representation affordable while giving you a clear understanding of the total expected cost, payment schedule, additional expenses, and services included.
Start by asking whether the attorney offers installments, a reduced retainer, flat-fee payments, contingency representation, limited-scope services, or financing. Compare each option using total cost rather than monthly payment alone, and get the fee arrangement clearly documented.
If private representation remains unaffordable, explore legal-aid and other low-cost assistance instead of assuming professional legal help is completely out of reach. Because attorney-fee rules and available arrangements differ by jurisdiction and type of case, treat general payment information as a starting point and rely on the written agreement and applicable local rules for your specific situation.


